
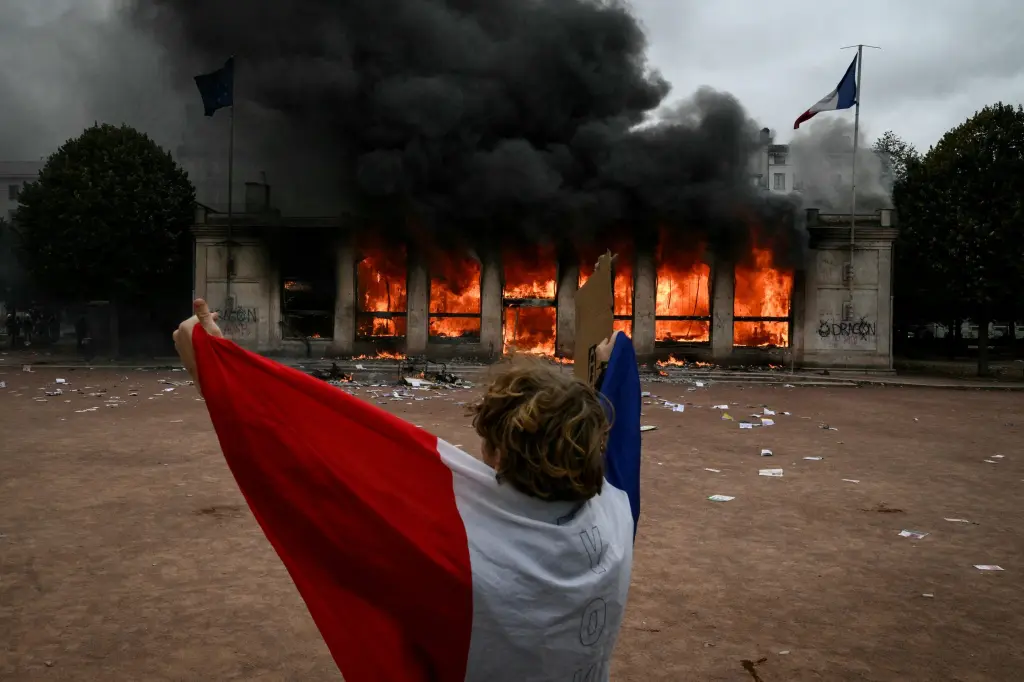
France's long-simmering debt crisis spilled into the streets this week, as nationwide protests over the cost of living coincided with a critical budget vote in the National Assembly, with unrest in some cities escalating into looting and fires at public buildings.
The fiscal backdrop is stark. French public debt has climbed to roughly $4 trillion, about 119 percent of GDP, the highest level since the Second World War. Bond yields have risen to their highest in 24 years, reflecting investors pricing in growing odds of a sovereign default and a broader loss of confidence that either the far-right or far-left blocs currently gaining influence in French politics would actually address the underlying fiscal imbalance if they came to power.
The government's proposed 2027 budget aims to narrow the deficit to 5 percent of GDP from the current 5.4 percent, a target now hanging on a knife-edge vote in the National Assembly. Prime Minister Sébastien Lecornu's budget faces a critical test this week, with its fate resting partly on whether far-right leader Marine Le Pen's party chooses to abstain rather than vote it down. Le Pen's bloc has pushed to lower the retirement age back to 62, while the far left has floated having the central bank cancel government debt outright, proposals that have done little to reassure bond markets already on edge.